


Hong Kong passes law requiring crypto exchanges to report customer transactions to tax authorities
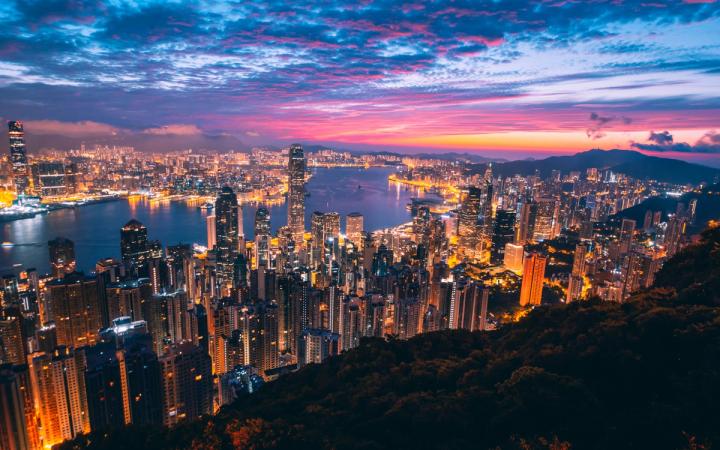
Hong Kong has passed a law requiring crypto exchanges and other covered service providers to collect customer and transaction data for tax purposes from 2027, with the information to be automatically shared with overseas tax authorities from 2028.
The government said the rules will take effect in 2027 and that the first exchanges of information between tax authorities will begin in 2028.
The law adopts the Organization for Economic Co-operation and Development's (OECD) Crypto-Asset Reporting Framework (CARF), released in October 2022 and designed to help governments identify crypto transactions that may otherwise go unreported for tax purposes.
Crypto exchanges and brokers covered by the rules will have to record customers' names, addresses, tax residency, and identification numbers, along with records of crypto purchases, sales, and transfers.
That includes buying and selling cryptocurrencies, swapping one token for another and sending funds to external wallets. The Inland Revenue Department will share customer details and annual transaction totals with tax authorities in participating jurisdictions where those customers are tax residents.
Hong Kong introduced licensing requirements for crypto exchanges in 2023. Under the new law, exchanges must also report customer transactions to overseas tax authorities.
Christopher Hui, Hong Kong’s secretary for financial services and the treasury, said the rules would help combat cross-border tax evasion.
Hong Kong has exchanged financial account information with overseas tax authorities under the OECD's Common Reporting Standard since 2018. Amendments extending that system to more digital financial products will take effect in 2028, with information exchanges beginning in 2029.
The Inland Revenue Department said it will issue guidance and provide technical support to help firms comply.

 BTC
 TRX
 RIOT
