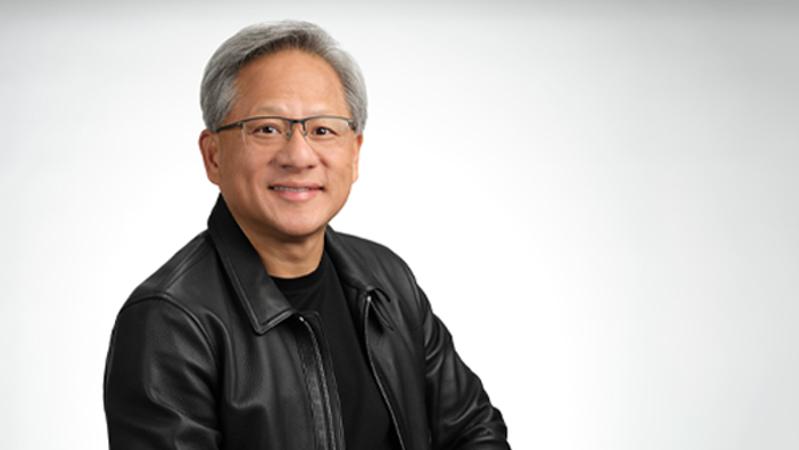
Jensen Huang's Crypto Past: From "Crypto Hangover" to On-Chain Opening
 NVDA
Eight years ago, the crypto hangover made him change his tune. This time, it's the crypto market setting his price.
Author: Clow, Baihua Blockchain
TechFlow: As Jensen Huang's scandal continues to unfold and Nasdaq remains closed, on-chain derivatives and decentralized prediction markets have already begun pricing in NVIDIA. Looking back at history, this is hardly the first intersection between NVIDIA and the crypto world. Eight years ago, the miner exodus triggered a “crypto hangover” that halved NVIDIA's market cap.
From quietly tolerating miners scrambling to buy GPUs early on, to implementing software locks to restrict mining, to mining companies transitioning to take on billions of dollars in AI compute orders that feed back into NVIDIA, the dynamic and interest binding between the two sides have completely reversed. This article traces the nine-year love-hate entanglement between NVIDIA and the crypto circle.
On Sunday afternoon, while Nasdaq remained closed, the cryptocurrency market had already begun trading on Jensen Huang's scandal.
NVIDIA tracking contracts on-chain fell nearly 4% within an hour, as two prediction markets subsequently launched new odds on his departure.
Jensen Huang was never really part of the crypto circle. But eight years ago, it was precisely the crypto circle that drove NVIDIA's stock price down by half in a single quarter.
The tally has been calculated for nine years, and it still isn't complete.
Two Years Propelled by Miners
During the August 2017 earnings call, Huang said: “Cryptocurrency and blockchain will always be here, and they will get very big.”
Six months later, in an interview with Barron's, he repeated: “Crypto is real, it's not going away.”
He had the confidence to say so. During those two years, miners were NVIDIA's most undiscriminating buyers. In May 2018, CFO Colette Kress revealed that the company sold $289 million worth of crypto-specific products alone that quarter.
Three months later, that number plummeted to $18 million.
In November 2018, it was Huang's turn to backtrack: “The crypto hangover has lasted longer than we expected.”
Unsold GPUs piled up in distribution channels. NVIDIA projected Q3 revenue would only reach $2.7 billion, while Wall Street had expected $3.4 billion. Those who bought NVIDIA shares at the end of September saw their holdings drop by less than half before Christmas—a 54% decline, ranking last in the S&P 500 for the quarter.
The one who said it would always be here was him; the one who declared a hangover was also him. Only nine months separated the two statements.
The Tally Isn't Complete Yet
The stock price eventually recovered, but the lawsuits did not.
In May 2022, the SEC took the first hit. It ruled that NVIDIA's quarterly reports for two consecutive quarters in fiscal year 2018 highlighted massive growth in its gaming business without disclosing that a significant portion of that growth came from mining. NVIDIA paid a $5.5 million fine, neither admitting nor denying the allegations.
For NVIDIA, the fine was insignificant; the real trouble lay with investors.
In 2018, a group of investors sued NVIDIA, alleging the company concealed over $1 billion in GPU sales related to mining. The lawsuit stretched from Trump's first term to his second.
The initial dismissal was overturned on appeal, and NVIDIA appealed all the way to the Supreme Court. In December 2024, the Court sent the case back, stating simply “improperly accepted,” with no further explanation.
In March this year, U.S. District Judge Haywood Gilliam for the Northern District of California approved class certification, covering investors who purchased NVIDIA stock between August 2017 and November 2018. NVIDIA petitioned the Ninth Circuit for review, supported by amicus curiae opinions from organizations including the U.S. Chamber of Commerce, but the motion was denied on May 26.
Certification does not equate to a finding of liability. The case is now in the discovery phase, with no trial date set yet. The plaintiffs' core allegation is that NVIDIA publicly claimed it primarily sold dedicated mining cards to miners, whereas in reality, nearly two-thirds were its gaming GPUs, specifically the GeForce series.
In other words, what the plaintiffs want to prove is that many “gamers” back then were actually miners.
NVIDIA has never admitted to misleading investors. But eight years on, the exact volume of mining cards sold and to whom remains an unsettled ledger.
From Restricting Mining to Praising Bittensor
While Huang verbally insisted crypto would endure, the company was actively pushing it out the door.
In February 2021, NVIDIA placed a lock on its newly released GeForce RTX 3060: using drivers to cut Ethereum mining performance by half, while simultaneously launching a separate line of CMP mining cards exclusively for miners.
Matt Wuebbling, head of GeForce marketing, made it clear in a blog post: “We designed GeForce for gamers.” The implication was straightforward: leave the gaming cards for players, and send miners to buy CMPs.
Ironically, a developer driver released by NVIDIA weeks later accidentally bypassed the lock, which the company subsequently acknowledged and patched.
CMP mining cards generated $550 million in fiscal year 2022, less than one-twentieth of the $12.4 billion generated by its gaming business that same period. By September 2022, Ethereum's shift to proof-of-stake eliminated the need for GPU mining, bringing this business chapter to a close.
Half a year later, NVIDIA CTO Michael Kagan told The Guardian that crypto “brings nothing useful to society,” whereas AI does.
This wasn't Huang speaking, but the CTO. ChatGPT had just gone viral, and NVIDIA's GPUs had already found a new batch of buyers.
The turning point arrived in March this year. During the GTC conference, Huang appeared on the All-In podcast, where host Chamath Palihapitiya brought up Bittensor. It's a network that rewards users with tokens for contributing computing power to collectively train AI models. Huang endorsed the concept of distributed training, viewing it as complementary to closed-source models.
That month, TAO rose from around $180 to over $332.
He praised the technical approach, not the token. But shifting from the CTO’s “useless” to the CEO’s nod signaled a change in how NVIDIA describes the crypto circle: no longer a pack of miners scrambling for GPUs, but a group leveraging compute for AI.
Miners Become Major Clients
NVIDIA is changing, but miners are adapting faster.
The reason isn't complicated: mining is getting increasingly unprofitable. CoinShares data shows that in Q4 2025, the weighted average cash cost for public mining companies to mine one Bitcoin was approximately $80,000.
Mining farms possess electricity, land, and server rooms—resources AI companies desperately lack. By the end of March this year, publicly traded Bitcoin mining companies had signed AI and high-performance computing contracts totaling over $70 billion.
IREN has gone the furthest. In November 2025, it signed a five-year, roughly $9.7 billion contract with Microsoft to supply compute power using NVIDIA's GB300 GPUs.
In May this year, it signed another five-year, roughly $3.4 billion deal with NVIDIA to provide GPU cloud services to NVIDIA's internal AI and research teams at its Childress campus in Texas. In the same transaction, IREN granted NVIDIA a warrant allowing the purchase of up to 30 million shares at $70 per share over five years, representing about $2.1 billion if fully exercised.
Eight years ago, miners competed with gamers for NVIDIA's GPUs. Now, a Bitcoin mining company is supplying compute power back to NVIDIA, and NVIDIA might even become its shareholder.
The roles have completely flipped.
The upside is stabilized orders, but the cost is that mining firms' equipment, clients, and financing are now more tightly bound to NVIDIA.
A Scandalous Weekend: Crypto Markets Open First
And then came this past weekend.
On October 29, Reuters/The New York Times reported that U.S. intelligence officials believed former Megaspeed executive Alice Huang had been funneling information to Beijing, noting her close ties to Jensen Huang.
The Chinese Embassy in the U.S. dismissed it as “baseless smearing,” while Singapore's Ministry of Home Affairs stated it had not investigated Alice Huang, though the Megaspeed case remains under investigation.
On Sunday, November 8, NVIDIA's board announced an independent investigation while stating there was no reason to believe national security or corporate secrets had been compromised. That same day, Jensen Huang posted a letter on the company website admitting to an extramarital affair: “What I did has no excuses, and I am deeply sorry.”
Nasdaq wouldn't open until Monday, but crypto markets jumped in first.
On Hyperliquid, a perpetual contract tracking NVIDIA's stock can trade over the weekend when traditional US markets are closed. After the news broke, the timeline unfolded as follows:
At 3:03 PM ET, on-chain NVIDIA began selling heavily.
At 3:22 PM, Kalshi launched three new markets, including one on whether Jensen Huang will step down before January 1, 2027.
At 4:17 PM, Polymarket went live with a market asking: “Will Jensen Huang announce his resignation or be fired by year-end?”
In less than ninety minutes, all three markets were live.
On-chain trading volume suddenly spiked. Weekdays previously averaged just over $500,000 per hour. From 3 PM to 8 PM, hourly volume reached about $24.5 million—a forty-fold increase.
Starting at 6:57 PM ET on Sunday, the price stalled at exactly $179.27 for ten full minutes. This sits precisely 5% below the reference price, acting as a hard floor permitted by weekend trading rules. The price couldn't drop further until after 8 PM, when overnight sessions reopened and external quotes resumed, finally breaking below that threshold.
As of the afternoon of November 9 Beijing time, the probability implied on Polymarket for his departure by year-end was 15%, while Kalshi priced his departure before January 1, 2027, at 18%.
There are two ways to interpret these numbers.
One reading is that NVIDIA and the crypto circle are deeply intertwined: the miners of yesteryear are now its clients and compute suppliers, and when trouble strikes, the on-chain market prices it in first.
The other reading is that this is just another celebrity-driven speculation cycle: that Polymarket market generated only about $150,000 in volume, a drop in the bucket against NVIDIA's multi-trillion dollar market cap, and the standalone on-chain contract pricing lasted barely five hours.
US markets open at 10:30 PM Beijing time tonight. NVIDIA will release its Q3 earnings in the early hours of November 18, and the independent investigation remains without a timeline.
Eight years ago, the crypto hangover forced him to backtrack.
This time, it's the crypto circle pricing him in.
Citește originalul pe Techflowpost
Mai multe știri
 BTC
 HYPE